Tax Publications - Page 9

Oman VAT FAQs

Oman VAT FAQs

Together with the other Gulf Cooperation Council (GCC) States, Oman has signed up to the Common VAT Agreement of the States of the GCC (GCC VAT Framework) which commits it to implementing a generally common VAT system by issuing national VAT legislation.

Click here: Oman VAT FAQs
Kuwait VAT FAQs

Kuwait VAT FAQs

Kuwait has not yet implemented a domestic VAT or Sales Tax Regime. However, together with the other GCC States, it has signed up to the GCC VAT Framework and therefore has committed to implement this common VAT system through national VAT legislation in the near future.

Click here: Kuwait VAT FAQs
VAT on healthcare comparatively in the GCC

VAT on healthcare comparatively in the GCC

Below we analyse in a comparative manner how the VAT regimes apply to the health care sector in the GCC Member States which have implemented VAT so far, which are the UAE, KSA, Bahrain and Oman. As for Qatar and Kuwait, we are still expecting further announcements from the governments there as regards to the timeline of the implementation. It is still expected they will implement at some point.

Click here: VAT on healthcare comparatively in the GCC
A state of play on tax litigation in KSA

A state of play on tax litigation in KSA

In recent years, the Kingdom of Saudi Arabia (KSA) has gone through tremendous reforms, and tax and the Customs authorities were part of this. Going from Department of Zakat and Income Tax (DZIT) to the General Authority of Zakat and Tax (GAZT) to the Zakat, Tax and Customs Authority (ZATCA). The tax administration went from a Department to an Authority (important semantic difference), and merged with the Customs authority.

Click here: A state of play on tax litigation in KSA
Tax in the GCC - An accounting or a legal matter?

Tax in the GCC - An accounting or a legal matter?

Consultants are worth their money and are selected on previous experience, trust or value for money. Consultants are mostly appointed to have a second pair of eyes. The respondents mostly expect salary differences to level out in the long run. They like to handle VAT filing in the tax department, and consider that the role of that tax department is to support the business in the most efficient way. The bigger the company, the more tax people, and they want to be accountable mainly to the CFO. Tax directors feel undervalued in terms of their remuneration and underestimated.

Click here: Tax in the GCC - An accounting or a legal matter?
Special Tax Payers in the GCC: Exempt taxable persons

Special Tax Payers in the GCC: Exempt taxable persons

The four GCC countries which have introduced VAT so far, UAE, KSA and Bahrain, have based themselves on the GCC VAT Treaty to draft their laws. There is a special group of VAT payers, which have a special capacity as stakeholders in the VAT system. They sit on the fringes of the VAT system, not being a full on taxable person, and neither simply a payer, like private persons would be. In the EU, this special group is sometimes called the “group of four”, or the “persons benefiting from an exception regime”. Together with the capital assets scheme, it is one of the more technical matters in VAT, and its status under GCC VAT is at a minimum lacking in clarification. In a previous article, we explored the status of the non taxable legal persons (https://aurifer.tax/news/non-taxable-legal-persons-in-the-gcc-may-need-to-register/?lid=482). In this article, we cover the exempt table persons. In the upcoming articles, we will be covering also the other special categories of taxable persons. Going forward we will refer to them as “special tax payers”.
Click here: Special Tax Payers in the GCC: Exempt taxable persons
Pillar Two and the GCC – Important consequences for tax havens and exemptions for nationals

Pillar Two and the GCC – Important consequences for tax havens and exemptions for nationals

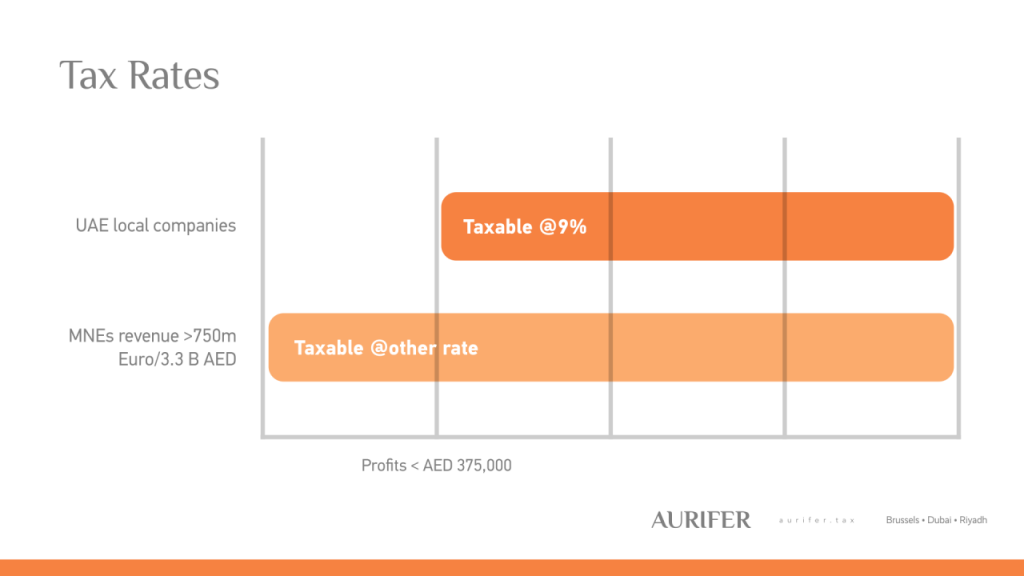
The same thing is happening with Pillar One and Pillar Two as with BEPS. Initially, it seemed to be a topic for insiders, tax administration officials and a handful of academics, but eventually it became a topic for everyone. Discussions around Pillar One and Pillar Two have picked up very considerable speed since the endorsement by the G7 on 5 June 2021, and the endorsement by most of the Inclusive Framework members on 1 July 2021. With laws being drawn up in 2022, and an implementation in 2023, Pillar Two is right around the corner. In this article we analyse Pillar Two. We will leave an analysis of Pillar One for next month’s article.

Click here: Pillar Two and the GCC – Important consequences for tax havens and exemptions for nationals