Categories
GCC Tax

Non taxable legal persons in the GCC may need to register

Non taxable legal persons in the GCC may need to register

The three GCC countries which have introduced VAT so far, UAE, KSA and Bahrain, have based themselves on the GCC VAT Treaty to draft their laws. The next country to do so, Oman, has done the same.

There is a special group of VAT payers, which fulfill a particular role as stakeholders in the VAT system. They sit on the fringes of the VAT system, not being a full on taxable person, and neither simply a payer, like private persons would be.

In the EU, this special group is sometimes called the “group of four”, or the “persons benefiting from a special regime”. These are the non taxable legal persons, the exempt tax payers, the small business and the farmers.

Together with the capital assets scheme, it is one of the more technical matters in VAT, and its status under GCC VAT is lacking clarification. Below, we explore the status of the non taxable legal persons. In the upcoming articles, we will be covering the other categories of special taxable persons in the GCC, which are listed below. Going forward we will refer to them as “special tax payers”.

GCC VAT and its origins

While not explicitly stated, the origin of the GCC VAT Framework (or “Common VAT Agreement of the States of the Gulf Cooperation Council” in full) lies in the EU VAT directive 2006/112/EC. More specifically it corresponds to the version applicable after 2011 and before 2013. The reasons for drawing inspiration from the EU VAT directive are obvious. The GCC had ambitions to copy the EU model. 

For example, the Economic Agreements between the GCC States of 1981 and 2001 read like the Treaty of Rome, which established the European Union.

The GCC had ambitions to form a similar trade bloc like the EU. While it indeed negotiates free trade agreements together, internally it works in a different way. It tried to establish a currency union as well, but was unsuccessful, although given that the countries have pegged their currency (relatively closely to) the US dollar, in practice they may have implemented certain elements of the monetary union. One of the more eye catching provisions of the Economic Agreements is that GCC citizens are allowed free circulation within the GCC. Such free circulation is again exactly the same principle which applies to EU citizens.

In addition to wanting to follow in the footsteps of the EU politically, there is another good reason to incorporate EU VAT provisions. The EU has the oldest VAT systems, and has the oldest VAT systems integrated in a customs union (see https://aurifer.tax/news/the-challenges-of-drafting-tax-legislation-and-implementing-a-vat-in-the-gcc/?lid=482&p=15 for a discussion on the genesis of the laws).

The copy is never better than the original

Like VHS tapes, the copy is never better than the original. This holds even more true when the copy is made from an old original. The GCC VAT Treaty does not incorporate the important changes to the EU VAT directive entered into force in 2013, 2015 and now in 2021.

At the same time, that does not necessarily need to mean that adverse consequences are triggered for the GCC States. The UAE has for example integrated the 2015 changes in its guidance and de facto applies them (see https://aurifer.tax/news/e-commerce-vat-rules-in-the-gcc-a-missed-opportunity-at-perfect-harmonization-with-the-eu/?lid=482). Bahrain has done the same in its guidance for the place of supply rules applicable to telecoms services.

A special group of tax payers

Like EU VAT, GCC VAT has two important main groups of stakeholders. They are the taxable persons on the hand and the private individuals on the other. The taxable persons are the businesses complying with VAT. That means they charge it, collect it and pay it to the tax authority. The private individuals are the consumers who carry the economic burden of the VAT and pay it to the businesses. They are the ones hit with the rise in cost.

Let us say that the taxable persons are “all in” and the private individuals “all out”. The private individuals (almost) have no obligation whatsoever. Although it may surprise, they have no legal obligations, except for their contractual obligations towards their contracting parties (and for imports made by private individuals).

There is another special group though. They often go by a special name even. In France, for example, they call them the persons benefiting from a special regime (“personnes beneficiant d’un regime derogatoire”). Elsewhere they may call them the “group of four”. In this article, we refer to them as the “special tax payers”.

Whether the special tax payers have VAT obligations or not, depends on their activity. The special tax payers in the EU are:

  • Small businesses
  • Exempt tax payers
  • Non taxable legal persons (including government bodies and charities)
  • Farmers and tax payers subject to a lump sum regime

Out of these four categories, the first two need to report VAT on services they receive from abroad. The last two need to report VAT on services they receive from abroad if they are already registered for VAT purposes because they have acquired goods from other EU Member States in excess of a threshold (between EUR 35,000 and EUR 100,000).

The special tax payers in the GCC are:

  • Small businesses (i.e. businesses below the mandatory registration threshold)
  • Exempt tax payers
  • Non taxable legal persons
  • Government bodies
  • Charities and Public Benefit Establishments
  • Companies exempt under international event hosting agreements
  • Citizens constructing their own homes
  • Farmers and fishermen

The taxable person concept in the GCC

The concept of taxable person in the GCC is where the GCC deviates from more mature VAT systems. In the EU, a taxable person is “any person who, independently, carries out in any place any economic activity, whatever the purpose or results of that activity”. Economic activity is then “Any activity of producers, traders or persons supplying services, including mining and agricultural activities and activities of the professions…”.

Although at first sight only subtly different, a taxable person in the GCC is “A Person conducting an Economic Activity independently for the purpose of generating income, who is registered or obligated to registered”. The last bit of the phrase is crucial.

In the EU, the registration is a consequence of the fact that an economic activity is conducted, it is not a defining element of it. Note also that it is a global concept in the EU, i.e. anyone in the world can be a taxable person. In the GCC, anyone in the world can conduct an economic activity, a subtle difference.

As a comparison, the GCC inspired itself on the UK definition of a taxable person, which is “A person is a taxable person for the purposes of this Act while he is, or is required to be, registered under this Act.”

VAT registration requirements

A Person is required to register for VAT purposes when resident in a Member State and making annual supplies in that State above the Mandatory registration threshold of SAR 375,000 (USD 100,000 or its equivalent in local currency). Non resident businesses making taxable supplies in a Member State need to be registered as from the first cents made.

A person can voluntarily register when resident in a Member State and making annual supplies in that State above the Voluntary registration threshold of SAR 187,500 (USD 50,000 or its equivalent in local currency), or incurring taxable expenses for the same value.

The GCC Member States have not deviated from this principle yet, although the UAE has set the forward looking threshold for the next 30 days instead of the next year (mimicking the UK).

Calculating the thresholds

According to the GCC VAT Treaty, and the Omani VAT law, in order to calculate the threshold, the following elements need to be included:

  • The value of taxable supplies, except for capital assets (category 1)
  • Value of goods and services supplied to the Taxable Person who is obliged to pay Tax (category 2)
  • The value of intra-GCC supplies which have a place of supply in another State but would have been taxable had they taken place in the State of residence (category 3)

The third category is not applicable right now, as none of the GCC Member States recognize each other as Implementing States.

The first category is straightforward, the second is much less so. The second category has been implemented in the UAE to take only into account imports of goods and services. In KSA, the receipt of reverse charged purchases are taken into account (which may include goods which are already in KSA when supplied by a non-resident and therefore not imported, contrary to the UAE). KSA and Bahrain also include deemed supplies in the calculation.

The second category mentions that the recipient must be a Taxable Person. It may be a Circular reasoning, since a business may not be a Taxable Person, but as a result of purchasing from abroad may become a Taxable Person and therefore may be required to register.

The first group of Special Tax Payers – the Non Taxable Legal Persons

In this series of articles, we will be covering the special tax payers in the GCC listed above, and their VAT obligations. We start with the Non Taxable Legal Persons.

This group of special tax payers is not explicitly mentioned in any of the GCC legislations so far. Its category is created following the application of the concepts of VAT law. 

It is possible that a legal entity, such as, but not limited to, LLC’s, PJSC’s, … is simply not in scope of VAT. Even though a company is usually set up to conduct business, in a number of a cases, it might not actually be conducting business from a VAT perspective. Such an entity would not constitute a taxable person.

There are a number of other situations as well though, where legal entities are in business but are not making supplies in the material scope of VAT (we are not covering supplies which are in the material scope of VAT but outside the GCC based on the place of supply rules).

Conducting an economic activity, or its colloquial term, being in business, is defined as “An activity that is conducted in an ongoing and regular manner including commercial, industrial, agricultural or professional activities or services or any use of material and immaterial property and any similar activity”.

The definition of economic activity is as broad as possible, and intended to encompass a maximum number of situations. It generally includes all types of commercial activities.

In regards to non-taxable legal persons, we therefore distinguish:

  • passive legal persons
  • legal persons in business but making material out of scope supplies

We discuss these in further detail below.

Passive legal persons and legal persons not in business

The first category could be described as passive legal persons. Although they are a legal entity and therefore potentially (or presumably) set up to conduct business, they do not do so. An example is a holding company, such as JAFZA offshore companies which are set up simply to hold shares or an asset (see https://aurifer.tax/news/more-often-than-not-jafza-offshores-need-to-register-for-vat/?lid=482&p=12 for a discussion on the matter). Another such an example is a charity not conducting business, a dormant company, or an entity only receiving subsidies.

Given the fact that they are not in business (not conducting an economic activity), they cannot qualify as a taxable person and therefore, they remain outside of the remit of the scope of VAT. 

This means that they are the equivalent of a final consumer, i.e. they pay the burden of VAT since they cannot recover any input VAT. Domestic input VAT incurred in the GCC is not deductible, and, importantly, they are not required to apply the reverse charge mechanism on any services they receive from abroad. 

In regards to import VAT, they are considered the equivalent of a consumer (but cannot benefit from certain import exemptions). For imports of goods by non-registered persons, the UAE’s FTA has stated that the payment of VAT needs to be made directly to the FTA, separately from the payment of customs duties. Alternatively, a non-registered person can use a courier company, with the latter unable to recover the import VAT.

Note that this is different in the EU, where this type of entities would have the obligation to pay VAT on services received from abroad, when it is already registered for VAT purposes, for example because it made intra-community acquisitions of goods from other EU Member States. Such a registration is an obligation, even if the entity does not make any other taxable supplies, but makes purchases from other EU Member States.

Legal persons in business but having materially out of scope income

A company could be conducting an economic activity, but not be making taxable supplies. An example is a business making investments in futures (although the UAE considers these exempt from VAT), recording unrealized capital gains, recording an appreciation of the value of a portfolio, or collecting dues from borrowers after purchasing a non performing loan portfolio. 

The question then begs what the VAT status is of such non taxable legal persons, if it is in business but not making taxable supplies.

When such an entity is conducting an economic activity, in order to calculate the registration threshold, this category would not have any income which counts towards taxable supplies (category 1 above).

However, one also needs to count the value of category 2. As mentioned above, there is some divergence between the approaches in the GCC States. Oman and Bahrain follow the GCC VAT Treaty, taking into accounts goods and services supplied to a Taxable Person who is obligated to pay VAT, whereas KSA takes into account the receipt of goods and services, and UAE only the “imports” of goods and services by Persons.

KSA confirmed its stance, and requires foreign businesses making supplies to non taxable persons (note it does not say “legal persons”) to register “where appropriate”. Presumably, GAZT means situations where the place of supply rules designate KSA as the appropriate jurisdiction to levy tax. GAZT confirms that if the recipient is carrying out an economic activity and the recipient is not registered for VAT purposes, the receipt of services will count towards the mandatory registration threshold.

In short, this category of legal persons, when it conducts an economic activity, needs to register for VAT purposes when it exceeds the registration threshold based on expenses or imports. It will then need to apply the reverse charge mechanism on services received from abroad, and be unable to recover that VAT.
Categories
GCC Tax

E-commerce VAT rules in the GCC: a missed opportunity at perfect harmonization with the EU?

E-commerce VAT rules in the GCC: a missed opportunity at perfect harmonization with the EU?

With the publication of an e-Commerce guide and a well established practice since the introduction of VAT on 1 January 2018, this webinar looks at the different aspects of VAT applicable on aspects of e-Commerce. We will give practical examples and show how to comply in practice with the rules. Given the enormous importance of the e-Commerce in the region, this webinar is a must attend for all tax practitioners.

Categories
GCC Tax UAE Tax

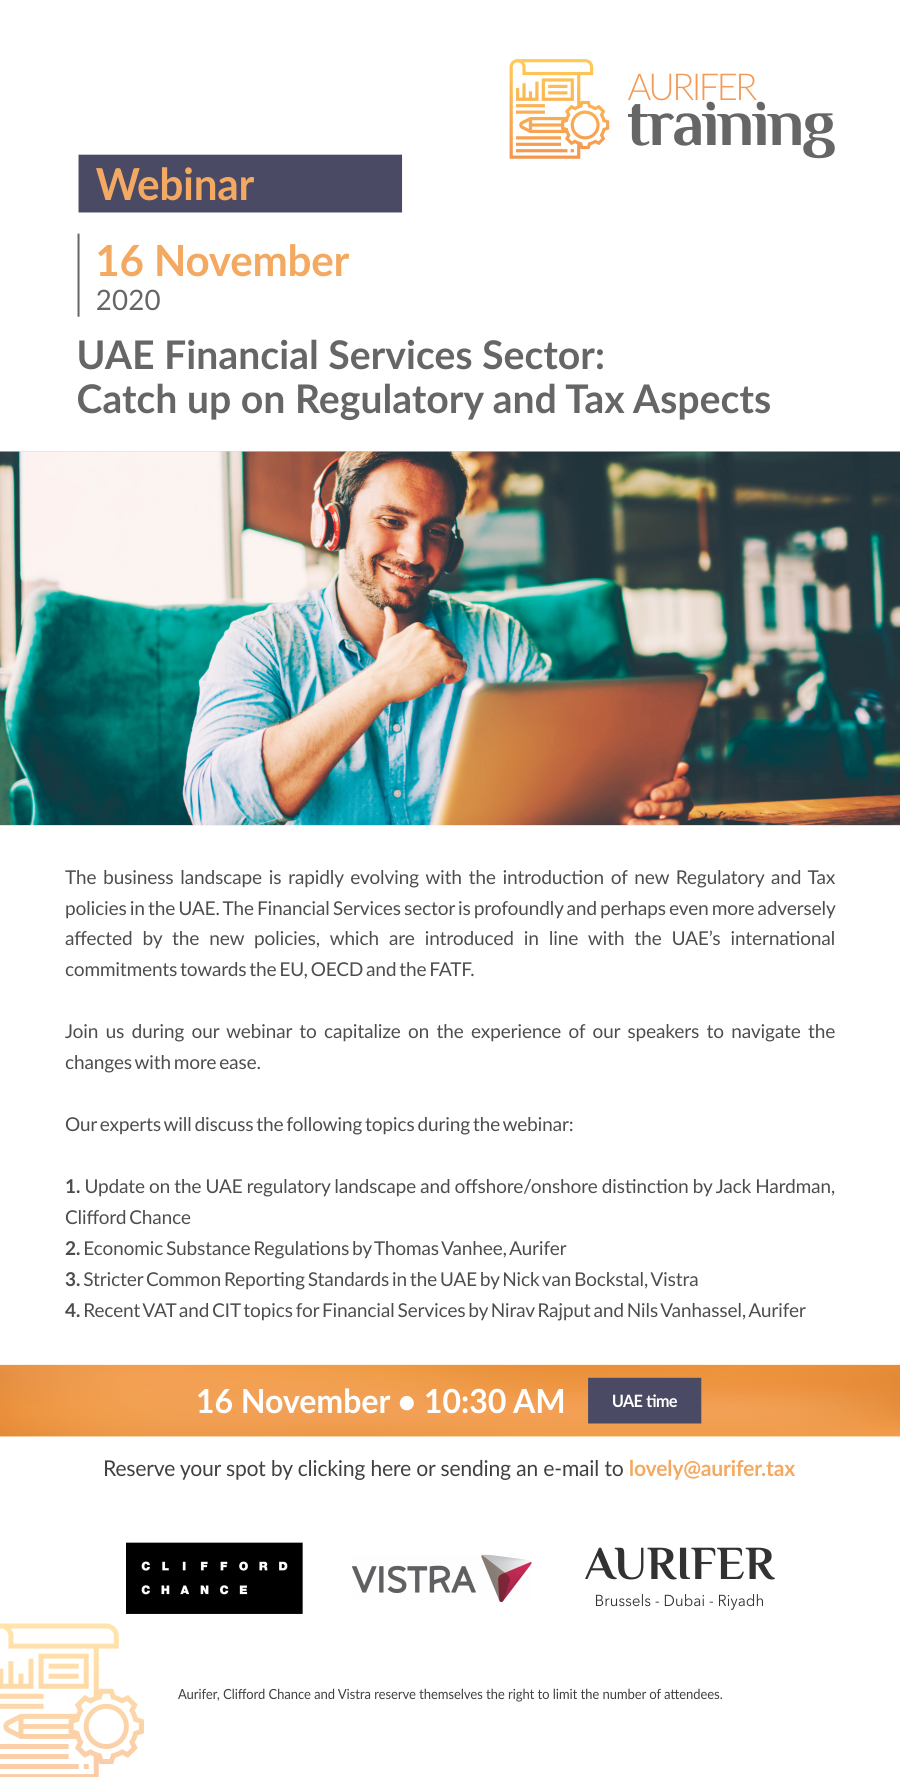
Financial Services Tax and Regulatory Webinar

Financial Services Tax and Regulatory Webinar

Register now for our Financial Services Tax and Regulatory Webinar via lovely@aurifer.tax

Categories
GCC Tax UAE Tax

Working remotely tax free – not that simple

Working remotely tax free – not that simple

The Government of Dubai launched a virtual working program for overseas employees wishing to relocate to Dubai whilst retaining employment in their respective countries. This program aims to enable individuals to utilize the economical and tax advantages associated with residing in Dubai, despite being employed in their countries. 

While seemingly very attractive, unfortunately it is not that easy for these employees to ensure that their salary will be tax free. In addition, every case may be different. Of course the UAE does not impose Personal Income Tax, but that does not mean that the other jurisdiction will let go that easily.

One can broadly distinguish the following scenarios: 

Scenario 1: No Double Taxation Treaty in place between UAE and country of employment 

Nothing shall prevent the application of the Personal Income Tax Law of the country of employment. That country shall retain the right to tax the person on his employment income (but may choose not to tax the employment income).  

E.g.: Jim is a US Citizen and and is employed by USCO. He decides to work from Dubai. The US tax authority still has the right to tax Jim.

Scenario 2: Double Tax Treaty in place between UAE and country of employment or tax residency and person does not qualify as tax resident in UAE

A non-resident in the UAE which is employed by a non UAE entity would still be taxed on his income in the state of his residence. Under the treaty, the country of residence would be obliged to provide double tax relief for taxes paid in the UAE. Even though the UAE has a primary right to tax, due to the fact that it does not tax employment income, the state of residence retains the right to tax the income of the employee. 

As an exception, in cases where the country of employment applies an exemption system, the person may not pay tax in the country of residence and exercise his employment tax-free in the UAE.   

E.g.: Roberto is a tax resident of country A, employed by a company incorporated in country A. Roberto moved to Dubai in December 2020 to benefit from the virtual working scheme. Roberto is not a resident in the UAE for tax purposes and is not aiming to be a resident in the UAE for the near future. 

The Double Tax Agreement between country A and the UAE applies the credit method to eliminate double taxation, which entails that country A shall deduct from the taxes calculated, the Income Tax paid in the UAE. As there is no Income Tax in the UAE, country A shall request the tax due in totality and fully retain its right to tax. 

The situation would differ if Roberto is a tax resident of country B and relocates to Dubai, and the Double Taxation Agreement between the UAE and country B applies an exemption method. Under the exemption system, any income which may be taxed by the UAE will be exempt from tax in country B. In the absence of the conditional subject to tax rule, the exemption system would effectively allow Roberto to escape the burden of Personal Income Tax in Country B, and pay no taxes in the UAE.

Scenario 3: Double Taxation Treaty in place between UAE and country of employment and the person qualifies as tax resident in the UAE. 

This situation may lead to a so-called Dual Residency issue, where two jurisdictions consider a person a tax resident. Given that the person in our assumption qualifies as a tax resident in UAE in addition to being a resident in his country of employment as well, the tie-breaker rule would apply to determine the residency of that person.  

On the basis of the tie breaker rule, it may not be that easy to consider a person who just moved as a tax resident in the UAE, if he still has his first home in the country of employment, and if his economic and social interest alongside his habitual abode are in the same country, and if he hold nationality in the country of employment. 

In case the person is considered to be a resident in the UAE under the tie-breaker rule, the UAE has the exclusive right to tax, even if such right is not exercised. The other country may argue however that the person is neither liable nor (effectively) subject to tax in the UAE. What happens next depends highly on the other jurisdiction’s tax policy.

Given that there is no Personal Income Tax in the UAE, there are also no domestic legal criteria to consider a person a tax resident in the UAE. There is however a means to obtain a tax residency certificate, based on criteria prescribed by the UAE Ministry of Finance. To obtain such a certificate, the applicant amongst others has to be resident in the UAE for a period exceeding 183 days, and submit an annual lease agreement documented by the competent authority. 

E.g.: Roberto in this scenario qualifies as a tax resident in the UAE and also in country A due to his employment ties in country A. Both countries may consider Roberto as a tax resident on under their domestic law. The dual-residency tie-breaker rule in the treaty between country A and the UAE, based on the OECD Model, dictates that Roberto’s residency shall be decided on the basis of:  

a) Place of permanent home. If in both/none of the states then; 

b) Centre of vital interest. If cannot be determined then;

c) Habitual abode. If in both/none of the states then;

d) Nationality. If national of both states;

e) Competent authority shall determine by mutual agreement.

If it is determined on the previous basis that Roberto is a resident of the UAE, he shall be taxed exclusively in the UAE because the job is executed in the UAE where he is resident even though the employer is resident in country A. 

As a consequence, Roberto will effectively not be subject to any Personal Income Tax.

Article by Thomas Vanhee, Faisal Alasousi and Mohamed Alaradi

Categories
GCC Tax VAT

Register now for our webinar on the brand new Omani VAT Law

Register now for our webinar on the brand new Omani VAT Law

On 12 October 2020, His Majesty Sultan Haitham bin Tarik issued Royal Decree 121/2020 to implement Value-Added Tax (VAT) in Oman. The Decree is expected to be published on the next official Gazette on 18 October 2020. Watch this space for the English translation.

The law will come into force 6 months after the publication, in April 2021. The standard VAT rate will be 5% and will be levied on most goods and services, with exceptions made to some supplies, which will be zero-rated or exempt.

The Omani law is a closer sister to the UAE VAT law and will follow the Bahraini law, applying hefty penalties, including, in some cases, imprisonment (i.e., failure to register for tax).

VAT is being implemented in response to severe financial and economic repercussions COVID-19 outbreak – amplified pre-existing fiscal strains and low oil prices. The IMF estimated generation of new revenue between 1.5 and 3 percent of non-oil GDP, from the introduction of VAT.

Taxpayers will have a little over six months of preparation time before the commencement date of the law.

The Executive Regulations will be published in December. Registration are expected to open in January 2021. Register for our webinar via lovely@aurifer.tax

Categories
GCC Tax

Ten days to go before the KSA Tax Amnesty ends

Ten days to go before the KSA Tax Amnesty ends

COVID19 had a profound impact on economies globally. KSA responded to the impact by increasing the VAT rate from 5 to 15% and take a number of economic measures to stimulate the private sector. The KSA tax authority, the General Authority of Zakat and Tax, also took a number of initiatives.

The GAZT initiatives contained several measures in respect to Zakat, CIT, VAT and Excise Tax. They included amongst others deferrals of import VAT, and additional delays to submit tax returns. One important feature though was that it contained a Tax Amnesty.

The Tax Amnesty is essentially a penalty waiver program under which tax payers can correct their position without being penalised. Such programs have proven to be hugely successful in other jurisdictions .

The initial deadline to make use of the Tax Amnesty was 30 June. Many tax payers took advantage of the deadline and managed to disclose their positions without penalties.

The deadline for the Tax Amnesty was subsequently extended to 30 September 2020 and is now set to expire in 10 days. It is likely that this is the last chance to benefit from this initiative, before GAZT steps up compliance enforcement. 

Under the Tax Amnesty, all Zakat, CIT or mixed Zakat and CIT paying entities would not be penalized for any failure to file, pay, or register late, provided they correct their positions before the end of the deadline and pay the taxes due. 

Some important penalties are for example:

  • Penalty for late VAT registration : 10,000 SAR
  • Late payment penalty for VAT : 5% to 25% of the liability in the tax return with an additional 5% for each month after this tax due 
  • Late payment penalty for CIT: up to 20K SAR per tax return and 1% for every 30 days.  

Given the impact of the latest Ministerial Decision amending the Income Tax By-Law , the Tax Amnesty has gained in importance. The change applies retroactively to 1 January 2020.

The amendment to the By-Law removes the limitation to consider a KSA company up to the second level of indirect ownership to determine its liability under Zakat or CIT. Such structures were already controversial and looked at closer by GAZT. It considered that in some cases tax payers “manipulated” share holdings to unlawfully obtain a (generally lower) Zakat liability instead of CIT. It treated such cases as tax evasion. 

Disclosing such a structure and paying the dues without penalties can only be done anymore for the next 10 days. The same holds for any other situation of non compliance in KSA.

Tax payers should act now, before GAZT steps its enforcement once the Amnesty Period ends.

Get in touch with our KSA tax team via thomas@aurifer.tax or faisal@aurifer.tax to know more.

Categories
GCC Tax VAT

Oman introduces VAT – Attend our webinar with the latest direct and indirect tax developments in Oman

Oman introduces VAT – Attend our webinar with the latest direct and indirect tax developments in Oman

Register for our webinar on 30 July and know all about the latest developments.

VAT will be implemented in the short term and many other tax changes will happen in the next few months. Aurifer and OH law are happy to invite you to our free webinar where we will discuss the tax developments in the Sultanate of Oman. We will cover the new VAT law and developments in terms of direct and indirect taxation.

Reserve your spot by sending an e-mail to lovely@aurifer.tax. Aurifer and OH Law reserve themselves the right to limit the number of attendees.

Categories
GCC Tax

KSA Tax Update Webinar

KSA Tax Update Webinar

On 27 May we will be organizing our KSA Tax Update Webinar covering the recent 15% VAT rate hike, tax amnesty measures, covid 19 measures and other updates. Register now for our webinar via lovely@aurifer.tax

For non GCC clients, we will be holding a second session at a more convenient timing, i.e. 6 pm UAE time (GMT+4).

Categories
GCC Tax

KSA’s GAZT labels corporate nominee structures as tax evasion – it is a good time to fix them

KSA’s GAZT labels corporate nominee structures as tax evasion – it is a good time to fix them

In this article the authors discuss common structures which are set up by non-GCC businesses to invest in KSA. Sometimes these structures have as a primary or secondary objective to optimize their overall tax liability in KSA. These structures are subject to increasing risk and should be disclosed if they led to an underreporting of corporate income tax in KSA. Managing this risk and the associated exposures is now possible at reduced cost thanks to a new tax amnesty program which was recently announced by GAZT.

Tax landscape in KSA 

In the Kingdom of Saudi Arabia (“KSA”), there are two types of direct taxes. The first is referred to as Zakat, which is a (quasi-) taxation on Saudi individuals and companies based on the concepts of Islamic law. The second is a traditional Corporate Income Tax (“CIT”) levied on profit.

In order to determine whether a company is subject to Zakat or CIT, the shareholding structure must be analyzed. Companies which are fully owned by KSA or GCC nationals [1] are subject to Zakat. Where a company is owned by both non-KSA and KSA investors [2], the portion of taxable income attributable to the non-KSA interest will be subject to CIT [3], and the proportion which relates to the interest held by the KSA or GCC national goes into the basis on which Zakat is assessed.

Zakat is assessed at 2.5%, whereas the CIT rate is 20%. However, the base for the calculation of Zakat [4] vastly differs from the tax base for CIT purposes [5]. Generally, the total direct tax liability of a business in KSA is lower when it is subject to Zakat, compared to when it is subject to Corporate Income Tax. Much depends however on the profitability of a business, and its assets and liabilities.

Structures used for KSA tax optimization

In situations where it is deemed that the overall tax liability would be lower under the Zakat regime as compared with an effective taxation under the CIT regime, businesses have sometimes implemented corporate legal structures mainly aimed at circumventing applicable KSA foreign ownership restrictions to benefit from a favorable tax treatment as described above. However, such corporate structures are likely to be successfully challenged by GAZT as they do not reflect the economic reality and the spirit of the provisions set out in the KSA CIT laws and regulations.

 A common example of a structure which could be used for such purposes, is to set up a foreign holding company (“HoldCo”) which holds the shares of one or more companies with operations in KSA. In these structures, the majority or all of the shares in the HoldCo are (nominally) held by GCC nationals on behalf and to the account of the foreign investor, but the economic interests and other rights of the foreign investor are usually substantially protected through ‘side agreements’ or, more robust alternative structures whereby the GCC nationals agree, among other things, to waive all economic and legal rights to receive dividends, to exercise votes, and to receive any proceeds of the sale of the shares. The GCC nominees surrender these in favor of one or more foreign investors who are registered as legal minority shareholders, or perhaps not registered at all.

The above mentioned structure has the effect of optimizing the overall tax liability of the operational company in KSA, since it will for the most part be liable for Zakat as opposed to the generally less favorable CIT regime. However, we set out below the potential risks and issues with such structures which may be potentially challenged by GAZT.

Tax evasion or other purposes

The structure can serve different purposes, such as managing certain restricted activities in KSA. The structure, or its equivalent, has been in place for many years and only seems to have come in focus of GAZT in the last few years.

Up until recently, we also had no explicit formal and public standpoint from GAZT on the matter, although in informal communication and in individual files the structure was challenged. This changed recently when, on its website, GAZT has announced that manipulation of ownership of shares for the purpose of reducing the CIT or Zakat liability of the company qualifies as tax evasion [6]. It should be noted, however, that the KSA CIT legislation does not define what exactly is to be considered as ‘manipulation’ of ownership of shares.  

Based on the above interpretation by GAZT, we are of the view that the use of a side agreement or other similar agreements or structures designed to create a tax advantage by way of having a discrepancy between the legal and economic ownership (as described above) is likely to fall within the scope of tax evasion, provided that it has the effect of lowering the overall tax liability of the company in KSA.

The qualification of the so-called ‘manipulation’ as tax evasion is significant, because it implies that the normal statute of limitations will be extended. Instead of five years, GAZT would have ten years to issue or amend an assessment [7]. In addition, penalties up to 25% of the unpaid tax may be imposed by GAZT [8].

Detection risks

GAZT has an increasing numbers of tools at its disposal, both formal and informal. Historically, it relied much on informal tools and anecdotal discoveries.

The informal tools were the informal exchanges between the KSA and foreign tax authorities. Although these cannot constitute the basis for an additional assessment, they did provide valuable information. The complexity though was that data was not always available or is sometimes scattered (e.g. in the UAE between different authorities).

Double Tax Treaties generally also provide the basis for a broad exchange of information provision. KSA can therefore request information to the foreign Ministry of Finance.

For the bigger international companies, the country by country reports (CbCr) filed can be a source of information. Since these should follow the economic realities reflected in the financial statements, a 100% nominally GCC held business with a side agreement would not feature in the CbCr report of the GCC shareholders (if they need to file one).

The local country files, also compulsory in KSA, except for 100% Zakat payers, may also provide some information.

GAZT is allowed to re-characterise any transactions whose form does not reflect its factual substance and status. With some imagination, GAZT may also estimate a formal Zakat payer’s liability with respect to Corporate Tax thus shifting the burden to the tax payer to demonstrate the contrary.

Untangling structures and KSA’s Voluntary Disclosure Initiative

It is not easy to untangle such structures. It requires at a minimum a change of ownership, e.g. of the Holding company or the set up of a new company. Often the structure is amended or disclosed through informal proceedings with GAZT. Upon disclosure, GAZT will impose discretionary penalties.

GAZT has recently announced a broad-based tax amnesty program with respect to income tax, withholding tax, VAT and excise tax (“Initiative”). The Initiative is effective as from 18 March 2020 until 30 June 2020 (“Initiative Period”). Any voluntary disclosures made during the Initiative Period will not lead to any penalties being imposed by GAZT (this includes penalties for late payment, penalties for delay in submitting the tax return and penalties for making amendments to the tax return). In other words, any penalties which would otherwise be due under normal circumstances (i.e. in case of a tax audit), will be waived by GAZT, provided that the taxpayer submits a voluntary disclosure during the Initiative Period. 

Taxpayers who are using (similar) tax optimization structures such as the ones that have been discussed in this article should consider making a Voluntary Disclosure to GAZT during the Initiative Period (18 March 2020 to 30 June 2020) in order to benefit from a waiver of penalties under the tax amnesty program.

With increasing detection risks and awareness at GAZT, we highly recommend to revisit the structures put in place in the past to mitigate their risks and get a tabula rasa with the KSA tax authorities.


[1] Citizens of the Gulf Cooperation Council (“GCC”) are considered as Saudi nationals for KSA tax purposes.

[2] In principle there is no minimum Saudi ownership requirement, however there are restrictions with respect to certain regulated activities banking, financing, insurance or regulated investment activities.

[3] Article 6 (a) of the Cabinet Decision No. 278/1424 On the Approval of the Income Tax Law.

[4] The computation of Zakat is complicated, but it is essentially an assessment on net income or net worth. Zakat can either be calculated through the direct method (net of Zakat able assets method) or the indirect method (sources of funds method).

[5] Broadly speaking, CIT is assessed on net profits, i.e. taxable income minus deductible expenses (articles 8 – 21 of the Saudi Arabia Cabinet Decision No. 278/1424 On the Approval of the Income Tax Law).

[7] Article 65 (b) of the Cabinet Decision No. 278/1424 On the Approval of the Income Tax Law.

[8] Article 77 (b) of the Cabinet Decision No. 278/1424 On the Approval of the Income Tax Law.

Categories
GCC Tax

COVID19 tax measures in the GCC

COVID19 tax measures in the GCC

Read our overview of the tax measures taken in the GCC in relation to COVID19. Our overview may be subject to daily updates.